 Institute of Advanced Investment Management

Masters Student Investment Fund
Current Fund (2026-2027)
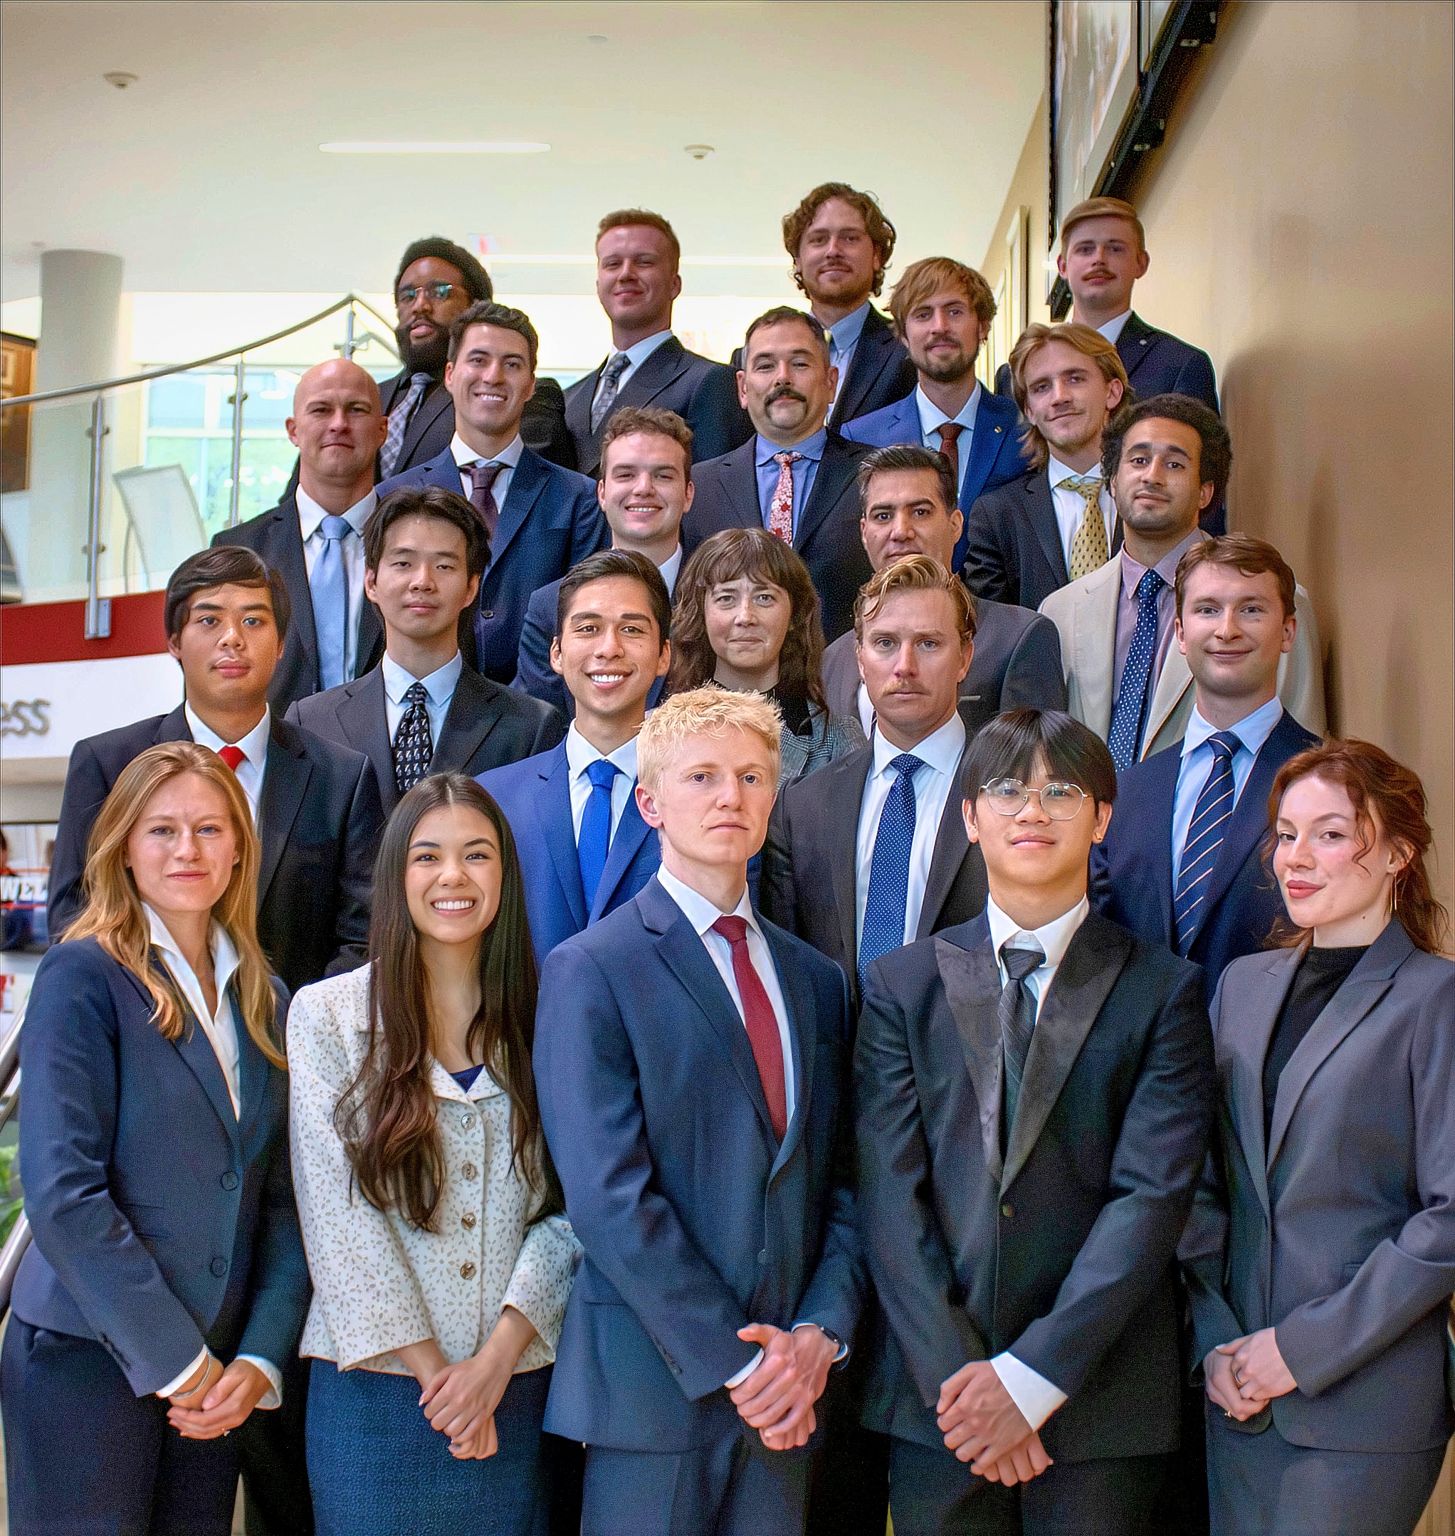
We are the third 2026–2027 Master’s Student Investment Fund (MSIF) cohort — building on the path the inaugural team created last year. They built the foundation, and now we’re strengthening the structure, improving the processes, and growing the culture for the students who will come next.
Our team is composed of graduate students from the United States, Norway, Brazil, pursuing degrees in Finance, Business Administration (MBA), Accounting, Real Estate, Data Analytics, and Information Systems.
We operate as a professional investment firm, structured into investment and operational teams. Our investment teams conduct market research, develop equity trading strategies, backtest ideas, and present investment pitches to our peer-led Investment Committee, where decisions are made by majority vote. Our operational teams manage fund administration, accounting, technology, marketing, transactions, and content management.
From research to execution, we manage every aspect of the fund, gaining hands-on experience in investment management, leadership, and strategic decision-making.
INVESTMENT PHILOSOPHY
MSIF employs a long-only equity strategy, integrating fundamental research, systematic analysis, and macroeconomic insights to construct a risk-adjusted portfolio. While our investment horizon is long-term, we incorporate short-term economic indicators to refine tactical positioning and optimize returns.
Each week, we assess domestic and global market trends, interest rates, currency movements, commodities, and sector performance (1-month and 12-month outlooks) to evaluate their impact on our holdings. Investment decisions are based on data-driven research, ensuring a disciplined and quantitative approach to security selection.
To maintain risk oversight, we conduct weekly portfolio reviews, monitoring sector weightings, exposure limits, and allocation imbalances. Our investment framework prioritizes capital preservation, risk-adjusted returns, and systematic rebalancing to ensure portfolio resilience in evolving market conditions.
FUND PARAMETERS & RISK MANAGEMENT
As portfolio managers, we establish investment parameters to align with market expectations for the academic year, ensuring a structured approach to portfolio construction, performance targets, and risk exposure. These parameters serve as a foundation for decision-making and portfolio governance. While they are reviewed and set at the beginning of each cohort, adjustments may be made in response to changing economic conditions or emerging investment opportunities.
Our risk-return framework balances long-term capital appreciation with active risk oversight, ensuring diversification, systematic rebalancing, and disciplined position sizing.
Performance & Risk Parameters
Performance Metrics
- Total Return Target: 10.5%-11.5% – Expected portfolio return for 2026 based on strategy and market conditions.
- Alpha Target: 1.5% – Extra return above the benchmark driven by active management.
- Sharpe Ratio: 1 – Measures risk-adjusted performance using total volatility.
- Treynor Ratio: 0.07 – Evaluates return earned per unit of market risk.
Risk Management
- Annualized Standard Deviation: 15.5% – Keeping track of portfolio volatility.
- Beta: 0.9 – 1.1 – Portfolio aligned with overall market risk.
- Maximum Drawdown: No more than 10% more than S&P 500.
- Idiosyncratic Risk Limit: < 20% – Controls company-specific volatility.
- Value at Risk (VaR): <9% – Controlling extreme losses.
Portfolio Constraints
- Single Stock Exposure Cap: 5%- 10% – Mitigating Idiosyncratic risk. If exposure equals 10%, it will trigger a rebalance.
- Industry Exposure Cap: 30% – Limits concentration in any single sector.
- Rebalancing Frequency: Quarterly – Maintains alignment with target exposures.
- Limit On Number Of Positions: 100 – Systematic strategy counts as a single “position”.
These parameters define our structured investment process, ensuring disciplined risk management while allowing flexibility in response to market conditions.
Leadership
Chief of Staff – Nicolas Maldonado
Editorial – Olivia Johnson
Marketing – Gorden Yang
Technology – Ilya Kulikov
Treasury –
Portfolio Managers
Bull Market Pros
Connor Jones
Abozar Mohammadi
Chanphone Visathip
Ragnarok Returns
Olivia Johnson
William Mjelde
Reilly Collins
Null Lotus
Tristan Broadbent
Miles Adams
Ilya Kulikov
Max Chomic
Financial Potato Group
Gorden Yang
Nathan Sartnurak
Milan Magnusson
Kyle Goodale
Wizard Capital
Leo Gonzalez Hernandez
Carolina Mayumi
Nicolas Maldonado
Joshua Hicks
The Utes of Wall Street
Mica Feltl
Mikayla Wheeler
Jack Banker
Lucas D’Ambrosio
Faculty
Dr. Jonathan Brogaard
Professor